Before you sign your next international contract, is the structure behind it right?
International contracts can create questions that go far beyond the commercial terms – from which entity should sign and where revenue should be received, to international procurement, banking, substance and regional operations.
JurisTax is offering selected Nigerian energy businesses a confidential preliminary review to identify the structuring questions worth considering before a major cross-border contract, transaction or expansion proceeds.
Confidential · Obligation-free · No contract upload required
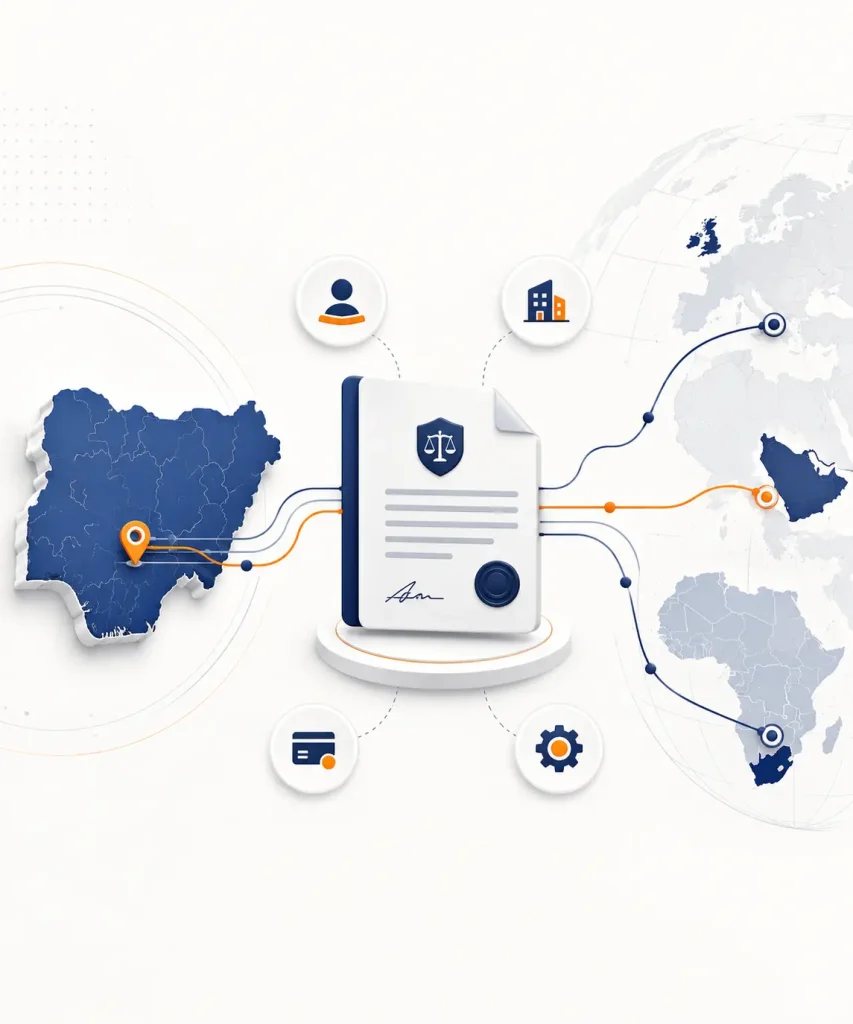
Cross-border contracts create questions before they create problems.
For Nigerian energy businesses, international growth often brings multiple entities, currencies, suppliers, clients and jurisdictions into the same transaction. The structure behind the contract needs to make commercial sense from the start.
International client
You are contracting with a client outside Nigeria or bidding for work in another jurisdiction.
Overseas suppliers
Equipment, technology or specialist services are being sourced and paid for internationally.
Foreign-currency revenue
A significant contract will be paid in USD, EUR, GBP or another foreign currency.
Regional expansion
Your business is beginning to operate, contract or invest across more than one country.
If two or more of these apply to your business, a preliminary structuring review may be worth considering.
Built for energy businesses with cross-border complexity
This review is most relevant where international clients, suppliers, payments, investors or operations are already part of the business – or are about to become part of it.
Oilfield Services
EPC / EPCIC
Engineering
Marine & Offshore
Drilling & Well Services
Equipment & Procurement
Energy Logistics
Exploration & Production Suppor
This review may be particularly useful if your business is:
- Entering into a major international contract
- Expanding into another African or Middle Eastern market
- Receiving significant foreign-currency payments
- Working with international suppliers, partners or investors
- Reviewing whether the current group structure still supports international growth
The questions behind the contract matter as much as the contract itself
The preliminary review focuses on the commercial structure around the transaction – identifying the areas that may need closer tax, legal, banking, regulatory or operational consideration.
Contracting Entity
Which company should enter into the contract, and does that reflect where the commercial activity, management and risk actually sit?
International Payments
Where will revenue be received, and where will major supplier, equipment and operating costs be paid?
Suppliers & Procurement
Are equipment, technology or specialist services being sourced internationally, and how does that affect the wider transaction structure?
Geographic Activity
Where will the work actually be performed, managed and controlled – and across which jurisdictions?
Ownership & Investment
Are foreign investors, shareholders, financing partners or joint-venture arrangements involved in the transaction or wider business?
Substance & Commercial Purpose
If an overseas entity is being considered, does it have a genuine commercial role, appropriate activity and sufficient substance?
The objective is not to provide a complete solution at this stage. It is to identify the structural questions that deserve closer review before the transaction proceeds.
Confidential · Obligation-free · No contract upload required
We don’t start by asking where you should set up a company
We start with the transaction itself – where the work is done, where clients and suppliers are based, where revenue is received, how the business is managed and what commercial role each entity is expected to perform
Mauritius may be relevant where
-
Regional African investment or ownership is involved
-
International investors are entering African projects
-
A holding or investment structure is required
-
Cross-border investment administration is needed
-
The business is expanding across several African markets
The UAE may be relevant where
-
The business is contracting with Middle Eastern clients
-
International procurement or trading is involved
-
A regional commercial presence is needed
-
Gulf-based suppliers or counterparties are important
-
The business is expanding into the Middle East
The right answer may be neither - or both
A new entity should only be introduced where there is a genuine commercial reason for it. In some cases, the existing structure may already be appropriate. In others, different jurisdictions may serve different legitimate functions within the group.
A simple first step before a bigger decision
You do not need to upload a contract or prepare a full transaction pack. A high-level overview is enough for us to identify the main structuring questions that may need closer review.
Tell us about the transaction
Share a short overview of the contract, expansion plan or cross-border activity you are considering.
We identify the key questions
We review the information and identify the main commercial, structuring and jurisdictional issues that may need closer consideration.
We discuss the findings
Where relevant, we arrange a confidential 30-minute discussion to talk through the main points and answer initial questions.
You decide what happens next
If further legal, tax, regulatory, accounting or structuring work is needed, we explain the next steps. There is no obligation to proceed.
Cross-border structuring should follow the business - not the other way around.
JurisTax works with businesses operating across multiple jurisdictions to assess and implement structures that reflect their commercial activity, ownership, investment and operational requirements.
International Corporate Structuring
Mauritius Structuring
UAE Market Entry & Structuring
Holding & Investment Structures
Corporate Administration
Governance & Substance Support
Tell us about the transaction you are considering.
Request a confidential review.
Confidential preliminary discussion | No obligation to proceed | No contract upload required
Important information
The Cross-Border Energy Contract Review is intended for general informational purposes only. It does not constitute legal, tax, regulatory, financial or investment advice and should not be relied upon as a substitute for advice based on the specific facts and circumstances of a transaction.
Any proposed structure would be subject to further review of the relevant commercial, legal, tax, regulatory, banking and substance requirements in the jurisdictions concerned.